Instant Loan Calculator For Estimating Your Monthly Emi Costs
Taking a loan involves more than deciding how much money you need. Borrowers also need to understand how much they may have to repay every month and how the interest rate and loan tenure affect the overall cost. An Instant Loan Calculator can make this planning easier by providing an estimated EMI based on the loan amount, interest rate, and repayment period.
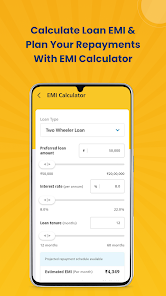
A Loan Calculator App can be useful when comparing different borrowing scenarios from a phone or other device. Similarly, a Personal Loan Calculator can help borrowers estimate monthly payments before applying for a personal loan. These tools do not guarantee a particular loan offer because the actual interest rate, fees, and approved amount depend on the lender and the borrower's eligibility.
Using an EMI calculator before applying can help you understand whether a proposed repayment fits your monthly budget. It can also help you compare different loan tenures and identify how changing the loan amount could affect your financial commitments.
Understand How an Instant Loan Calculator Works
An Instant Loan Calculator generally requires three basic inputs: the principal amount, interest rate, and loan tenure. After entering these details, the calculator estimates the monthly EMI.
Loan Amount
The loan amount is the principal you intend to borrow. A higher principal generally results in a higher EMI when the interest rate and tenure remain unchanged.
For example, if you need ₹2 lakh but apply for ₹3 lakh without a clear reason, you may end up paying interest on money you do not actually need. Calculating different amounts can help you identify a more suitable borrowing level.
Interest Rate
The interest rate determines how much interest is charged on the outstanding loan balance. Even a small difference in interest rates can affect the total repayment amount, particularly for longer tenures.
When using an Instant Loan Calculator, enter the interest rate offered or an estimated rate to understand the possible EMI. The final rate may differ after the lender completes its assessment.
Loan Tenure
Loan tenure refers to the period over which the loan is repaid. A longer tenure generally reduces the monthly EMI but may increase the total interest paid.
A shorter tenure can increase the monthly payment while potentially reducing the overall interest cost. Comparing both options can help you select a repayment period that fits your budget.
Use a Loan Calculator App for Quick Estimates
A Loan Calculator App can be convenient for borrowers who want to calculate EMIs while reviewing different loan options. Instead of manually calculating each scenario, you can change the loan amount, interest rate, or tenure and immediately review the estimated result.
Compare Multiple Loan Scenarios
Suppose you are considering a ₹1.5 lakh loan. You can enter different repayment periods to see how the estimated EMI changes.
You can also compare:
- Different loan amounts
- Different interest rates
- Short and long repayment periods
- Estimated monthly EMI
- Approximate total repayment
- Approximate interest payable
This makes it easier to understand the financial effect of changing one loan variable at a time.
Calculate Personal Loan Costs Before Applying
A Personal Loan Calculator can be particularly useful when planning an unsecured personal loan. Since personal loans are often repaid through fixed monthly EMIs, estimating the payment in advance can help with budgeting.
Check the EMI Against Your Monthly Income
Before borrowing, list your regular expenses, existing EMIs, household costs, savings, and other financial commitments. Then compare the estimated new EMI with the amount remaining each month.
The objective should not simply be to find the largest loan you can qualify for. Instead, consider an amount that you can reasonably repay without disrupting essential expenses.
Understand the Difference Between EMI and Total Loan Cost
The EMI tells you the amount paid periodically, but it does not tell the complete cost of borrowing by itself.
For example, a loan may have a manageable EMI because it has a longer tenure. However, extending the repayment period can result in more interest being paid over time.
When using an Instant Loan Calculator, consider both
Monthly EMI: The estimated amount payable each month.
Total repayment: The approximate principal plus interest paid over the full tenure.
Also account for applicable processing fees and other charges because these may not always be included in a basic EMI calculation.
Adjust the Loan Amount to Fit Your Budget
One of the most useful features of an EMI calculator is the ability to test different loan amounts.
If the estimated EMI is higher than your comfortable monthly budget, you can reduce the principal and calculate again. You could also consider whether a longer tenure would make the monthly payment more manageable.
Avoid Borrowing More Than Necessary
A larger loan may provide additional funds, but it also creates a larger repayment obligation. If the money is intended for a specific expense, estimate that expense carefully before deciding how much to borrow.
For planned purchases, compare the cost of financing with your available savings and other payment options.
Compare Interest Rates Carefully
Interest rates can differ between lenders based on factors such as credit history, income, loan amount, tenure, and internal eligibility criteria.
Use the calculator to understand the effect of different rates. For instance, enter the same loan amount and tenure at two different interest rates. The resulting EMI and total interest estimates can show why the rate matters.
However, the calculator should be treated as a planning tool rather than confirmation of the final loan terms.
Consider Additional Loan Charges
An EMI calculation may not include every cost associated with borrowing. Before accepting a loan, review the lender's complete fee structure.
Look for These Charges
Depending on the loan product and lender, costs may include:
- Processing fees
- Documentation charges
- Late payment fees
- Prepayment or foreclosure charges
- Applicable taxes
- Other service-related fees
Read the loan agreement carefully to understand which charges apply to your specific offer.
Use Calculations Before Submitting an Application
Using an Instant Loan Calculator before applying gives you an opportunity to review your finances without immediately committing to a loan.
Start by determining the amount you genuinely need. Then enter that amount into the calculator along with the expected interest rate and possible tenure. Review the estimated EMI and total repayment.
If the EMI appears difficult to manage, reconsider the loan amount or repayment period before submitting an application.
Keep Your Repayment Plan Realistic
A calculator can provide useful estimates, but your actual monthly budget should guide the final borrowing decision.
Unexpected expenses can arise during the repayment period. Therefore, avoid creating a repayment plan that uses almost all of your available monthly income.
Maintaining some financial flexibility can make it easier to handle regular expenses while continuing to make loan payments on time.
Conclusion
An Instant Loan Calculator is a practical tool for estimating monthly EMI costs before taking a loan. By entering the loan amount, interest rate, and tenure, borrowers can compare different repayment scenarios and understand how changes to these factors affect the estimated payment.
A Loan Calculator App can make this process convenient when you want to check calculations while comparing borrowing options. A Personal Loan Calculator can similarly help estimate the monthly cost of a personal loan before submitting an application.
Remember that calculator results are estimates, and the actual loan terms depend on the lender's assessment and applicable charges. Using these calculations alongside a realistic monthly budget can help you choose a loan amount and repayment period that you can manage responsibly.